Part 23 of 40 in The Crorepati’s Shoestring← Part 22Part 24 →
This chapter explains how keeping fixed costs low can give founders more time to learn what customers value and what delivery really costs. It helps founders test demand, supplier arrangements and business economics before taking on irreversible commitments.
- Separate irreversible obligations from costs that rise with sales.
- Use a pay-per-use supplier arrangement as a modest, observable test.
- Measure monthly break-even revenue, including time, cash, refunds and direct costs.
- Personally perform the least scalable work before automating it.
- A failed test is acceptable; an unmeasured test is merely activity.
The central argument
A low break-even point gives founders room to learn.
There is a temptation in the Indian startup ecosystem to turn an uncertainty into a capital request. The founder has not yet learned what the buyer values, how the product will be delivered, or how much it costs to fulfil one promise. A cheque may postpone these questions, but it rarely answers them. The better starting point is a test that forces reality to respond.
Frugality is not miserliness. It is disciplined resource allocation. Spend generously where quality, safety, trust or the customer outcome requires it; challenge spending that merely makes the company look more impressive. This distinction matters in an economy where an extra month of runway, an advance payment, or an honest conversation with a buyer can change a company’s future.
The practical decision in this chapter is specific: separate irreversible obligations from costs that rise with sales. It asks the founder to trade certainty of appearance for evidence of substance. Evidence may be awkward, disappointing or slower than a press announcement; it is still more useful.
Questions worth asking
- What would I have to observe to know that “a low break-even point gives founders room to learn.” applies here?
- What is the smallest reversible choice I can make this week?
- Which customer, worker or supplier knows something my spreadsheet does not?
Founder’s margin note: Describe the decision you have postponed because you hoped funding, hiring or a new tool would make it easier.
An Indian story
ILLUSTRATIVE COMPOSITE, a teaching scenario, not a documented account of a named company.
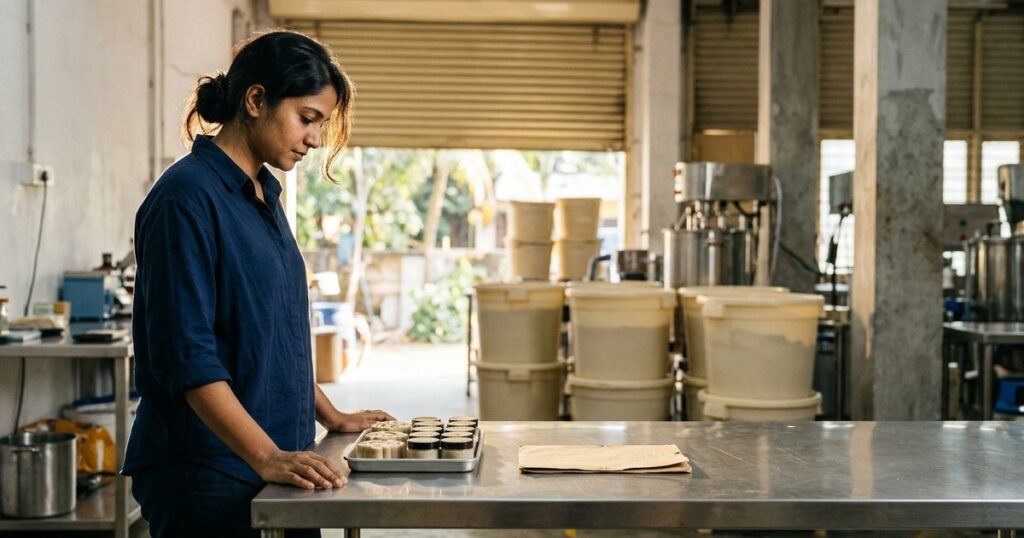
A Kochi brand rents batch production capacity instead of leasing a factory on day one.
Imagine meeting this founder on a hot afternoon with three phone calls missed and a supplier waiting for an answer. The problem is not a shortage of ideas. It is a shortage of clear priorities. The founder can buy a tool, hire a consultant or redesign the logo, but none of those actions will automatically uncover the customer’s actual need.
Instead, the founder chooses a modest, observable next step: negotiate one pay-per-use supplier arrangement. The purpose is not to win a case-study competition. It is to discover whether people change their behaviour when the offer is made, and what the economics look like after the founder does the work.
The signal to watch is monthly break-even revenue. A disappointing result is useful when it rules out an expensive path. A promising result is only a beginning: repeat it with customers who do not know you personally, on ordinary weekdays, without special favours.
Compare with documented Indian founders
Zoho and Zerodha are prominent examples of companies whose founders publicly discussed building without external equity funding. Their paths differ dramatically, and neither should be treated as a universal recipe. The transferable lesson is that control over pace and priorities can itself be a strategic asset. See the source note at the back of this book.
Field observation: Who in your district or industry already does this unusually well with limited resources? Ask permission to observe them.
The operating playbook
A seven-day field experiment
Day 1, Define Write the most dangerous assumption behind this chapter: A low break-even point gives founders room to learn. Name who could prove you wrong.
Day 2, Observe Watch three customers perform the task today; record actions and exact phrases, not your interpretation.
Day 3, Offer Make a concrete offer or test: Negotiate one pay-per-use supplier arrangement. Be clear about price, terms and expected delivery.
Day 4, Deliver Personally perform the least scalable part. Observe friction, mistakes and objections before automating.
Day 5, Count Measure monthly break-even revenue; include time, cash paid, refunds and all direct costs.
Day 6, Repair Look specifically for this trap: variable contracts that are unreliable or exploit workers. Change one thing, not the entire system.
Day 7, Decide Continue, modify or stop. State what evidence would reverse your decision next week.
The one-page scorecard
Hypothesis and customer segment: ______________________________
Cash spent / cash collected / money still owed: ____________________
Outcome metric and its baseline: ________________________________
Three observations that surprised us: ____________________________
Decision, owner and date of next review: _________________________
Rule: a failed test is acceptable; an unmeasured test is merely activity.
AI workshop & reflection
What to delegate to AI
Stress-test cost structures across three volume scenarios.
Copy-ready founder prompt
Act as a skeptical operating partner to an Indian bootstrapped startup. Our chapter principle is: “A low break-even point gives founders room to learn.” Our target customer is [segment], budget is ₹[amount], and our available time is [days]. We are considering this experiment: Negotiate one pay-per-use supplier arrangement. Identify hidden assumptions, a cheaper test, what evidence would disprove the idea, relevant India-specific customer frictions, and a quality checklist. Do not invent customer facts. Mark every assumption requiring human verification.
Check the output before acting
- Are all numbers sourced from my own records or clearly labelled assumptions?
- Have we checked local language, payment habits and distribution realities?
- Have we excluded customer identifiers and confidential commercial information?
- Does a human owner review any safety, legal, financial or reputational decision?
Your founder notebook
One belief I am willing to change: ________________________________
One real customer I will speak to: ________________________________
One experiment I will complete: ________________________________
My follow-up date: ________________________________
The point of AI is not to sound more certain. It is to become cheaper, quicker and more rigorous at discovering what is true.
Frequently asked questions
Why does a low break-even point help founders?
It gives founders room to learn. Keeping obligations reversible can provide more time to understand customers, delivery and fulfilment costs.
How can a founder test a supplier arrangement?
Negotiate one pay-per-use supplier arrangement with clear price, terms and expected delivery. Observe reliability, costs and any effect on workers.
What should be included when measuring monthly break-even revenue?
Include time, cash paid, refunds and all direct costs.
What should founders check before using AI for cost planning?
Check that numbers come from your records or are labelled assumptions. Exclude customer identifiers and confidential commercial information, and have a human review safety, legal, financial or reputational decisions.