Part 12 of 40 in The Crorepati’s Shoestring← Part 11Part 13 →
This chapter explains why payment terms should be treated as part of product design, especially for Indian startups managing customer credit, supplier advances and limited resources. It helps founders test customer behaviour and business economics before spending on tools, consultants or expansion.
- Payment terms can reveal customer value, delivery realities and fulfilment costs better than a capital request.
- Pilot milestone billing with five customers and measure days sales outstanding and overdue balance.
- Observe customers directly, personally handle delivery friction, and change one thing at a time.
- A failed test is acceptable, but an unmeasured test is merely activity.
- Use AI for payment reminders and assumption checks, while humans verify facts and decisions.
The central argument
Payment terms are product design, not just accounting.
There is a temptation in the Indian startup ecosystem to turn an uncertainty into a capital request. The founder has not yet learned what the buyer values, how the product will be delivered, or how much it costs to fulfil one promise. A cheque may postpone these questions, but it rarely answers them. The better starting point is a test that forces reality to respond.
Frugality is not miserliness. It is disciplined resource allocation. Spend generously where quality, safety, trust or the customer outcome requires it; challenge spending that merely makes the company look more impressive. This distinction matters in an economy where an extra month of runway, an advance payment, or an honest conversation with a buyer can change a company’s future.
The practical decision in this chapter is specific: choose milestones, deposits and reminders that match customer economics. It asks the founder to trade certainty of appearance for evidence of substance. Evidence may be awkward, disappointing or slower than a press announcement; it is still more useful.
Questions worth asking
- What would I have to observe to know that “payment terms are product design, not just accounting.” applies here?
- What is the smallest reversible choice I can make this week?
- Which customer, worker or supplier knows something my spreadsheet does not?
Founder’s margin note: Describe the decision you have postponed because you hoped funding, hiring or a new tool would make it easier.
An Indian story
ILLUSTRATIVE COMPOSITE, a teaching scenario, not a documented account of a named company.
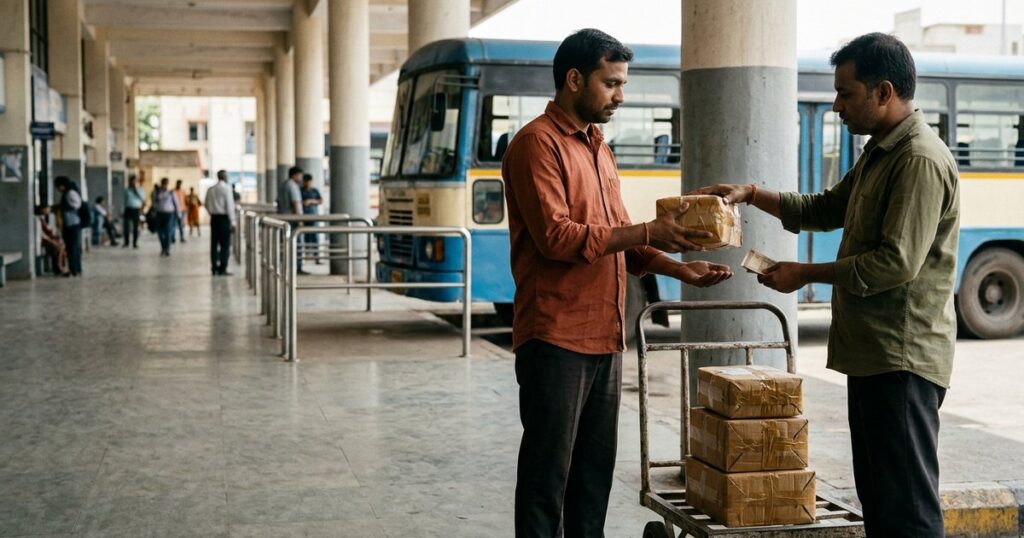
A tier-two-city wholesaler is profitable yet trapped between supplier advances and retailer credit.
Imagine meeting this founder on a hot afternoon with three phone calls missed and a supplier waiting for an answer. The problem is not a shortage of ideas. It is a shortage of clear priorities. The founder can buy a tool, hire a consultant or redesign the logo, but none of those actions will automatically uncover the customer’s actual need.
Instead, the founder chooses a modest, observable next step: pilot milestone billing with five customers. The purpose is not to win a case-study competition. It is to discover whether people change their behaviour when the offer is made, and what the economics look like after the founder does the work.
The signal to watch is days sales outstanding and overdue balance. A disappointing result is useful when it rules out an expensive path. A promising result is only a beginning: repeat it with customers who do not know you personally, on ordinary weekdays, without special favours.
Compare with documented Indian founders
The lesson should be tested in your own market rather than borrowed unquestioningly from a celebrated startup. A founder supplying small-town retailers faces different margins, credit terms and trust barriers from a software exporter. Copy a method of learning, not a famous company’s surface features.
Field observation: Who in your district or industry already does this unusually well with limited resources? Ask permission to observe them.
The operating playbook
A seven-day field experiment
Day 1, Define Write the most dangerous assumption behind this chapter: Payment terms are product design, not just accounting. Name who could prove you wrong.
Day 2, Observe Watch three customers perform the task today; record actions and exact phrases, not your interpretation.
Day 3, Offer Make a concrete offer or test: Pilot milestone billing with five customers. Be clear about price, terms and expected delivery.
Day 4, Deliver Personally perform the least scalable part. Observe friction, mistakes and objections before automating.
Day 5, Count Measure days sales outstanding and overdue balance; include time, cash paid, refunds and all direct costs.
Day 6, Repair Look specifically for this trap: pressuring vulnerable customers or hiding fees. Change one thing, not the entire system.
Day 7, Decide Continue, modify or stop. State what evidence would reverse your decision next week.
The one-page scorecard
Hypothesis and customer segment: ______________________________
Cash spent / cash collected / money still owed: ____________________
Outcome metric and its baseline: ________________________________
Three observations that surprised us: ____________________________
Decision, owner and date of next review: _________________________
Rule: a failed test is acceptable; an unmeasured test is merely activity.
AI workshop & reflection
What to delegate to AI
Draft courteous Hindi and English payment reminders.
Copy-ready founder prompt
Act as a skeptical operating partner to an Indian bootstrapped startup. Our chapter principle is: “Payment terms are product design, not just accounting.” Our target customer is [segment], budget is ₹[amount], and our available time is [days]. We are considering this experiment: Pilot milestone billing with five customers. Identify hidden assumptions, a cheaper test, what evidence would disprove the idea, relevant India-specific customer frictions, and a quality checklist. Do not invent customer facts. Mark every assumption requiring human verification.
Check the output before acting
- Are all numbers sourced from my own records or clearly labelled assumptions?
- Have we checked local language, payment habits and distribution realities?
- Have we excluded customer identifiers and confidential commercial information?
- Does a human owner review any safety, legal, financial or reputational decision?
Your founder notebook
One belief I am willing to change: ________________________________
One real customer I will speak to: ________________________________
One experiment I will complete: ________________________________
My follow-up date: ________________________________
The point of AI is not to sound more certain. It is to become cheaper, quicker and more rigorous at discovering what is true.
Frequently asked questions
Why are payment terms considered product design?
Payment terms affect customer behaviour, delivery, trust and the economics of fulfilling a promise. They are not only an accounting matter.
How can a founder test milestone billing?
Make a clear offer to five customers, including price, terms and expected delivery. Measure days sales outstanding, overdue balance, time, cash paid, refunds and direct costs.
What should founders measure in a payment experiment?
The chapter names days sales outstanding and overdue balance as key signals. The scorecard also records cash spent, cash collected, money still owed and the outcome metric baseline.
How can AI help with payment terms?
AI can draft courteous Hindi and English payment reminders and identify hidden assumptions, cheaper tests and evidence that could disprove an idea. A human should verify numbers, customer realities and safety, legal, financial or reputational decisions.